COSCO SHIPPING Specialized Carriers reported a 147.12% increase in third-quarter net profit attributable to shareholders, reaching RMB1.246 billion, as higher shipping revenue and an expanded specialised fleet supported its financial performance.
The Shanghai-listed company recorded third-quarter revenue of RMB8.189 billion, up 40.34% year on year, according to its financial results released on 29 October 2026.
For the first nine months of the year, attributable net profit reached RMB2.617 billion, an increase of 96.91% from the same period in 2025. The figure exceeded the company’s full-year 2025 attributable profit of approximately RMB1.780 billion.
Nine-month revenue increased 36.27% to RMB22.635 billion, while net profit attributable to shareholders excluding non-recurring gains and losses rose 91.35% to RMB2.565 billion.
The company attributed the revenue increase primarily to expanded vessel capacity and higher shipping business revenue.
Its owned and operating-leased fleet stood at 206 vessels with a combined capacity of 9.5813 million deadweight tonnes (dwt) as of 30 September 2026. This compared with 198 vessels and 9.1185 million dwt at the end of 2025.
During the third quarter, COSCO SHIPPING Specialized Carriers brought three newly built vessels into operation, comprising one heavy-lift ship, one car carrier and one asphalt carrier. Three older timber carriers were retired and disposed of during the same period.
The larger fleet handled 25.71 million tonnes of cargo during the first nine months, representing a 43% increase year on year.
The latest results follow substantial fleet expansion in 2025. According to the company’s annual report, 28 new-type multipurpose vessels, nine heavy-lift ships and 13 LNG dual-fuel car carriers were added to its operations during that year.
These 50 vessels represent additions to the operating fleet, rather than a verified total of company-owned newbuilding deliveries.
The annual report also shows the scale of the company’s specialised heavy transport business. At the end of 2025, its conventional heavy-lift fleet comprised 39 vessels, including 24 owned ships and 15 operating-leased units.
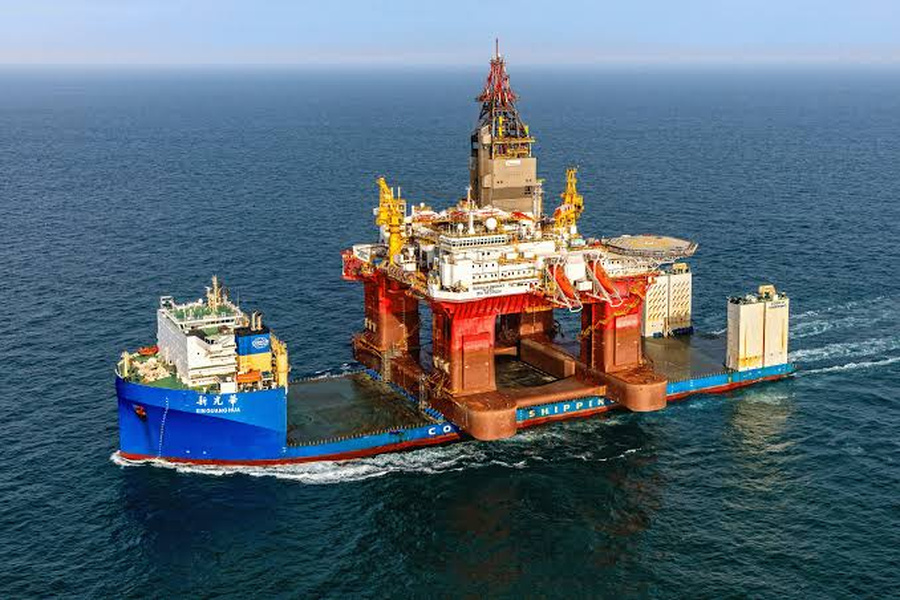
The company separately operated 10 owned semi-submersible heavy transport vessels, with a combined capacity of approximately 517,100 dwt.
The four principal specialised cargo segments reported different revenue and margin profiles in 2025.
The conventional heavy-lift segment generated RMB3.222 billion in revenue, with a gross margin of 27.01%. Semi-submersible heavy transport operations recorded revenue of RMB2.895 billion and a gross margin of 26.74%.
Conventional multipurpose vessels contributed RMB4.091 billion in revenue at a gross margin of 17.38%, while the new-type multipurpose fleet generated RMB5.957 billion with a gross margin of 13.05%.
The new-type multipurpose category principally covers open-hatch vessels used for pulp transportation and other cargoes. It is reported separately from the company’s conventional multipurpose and heavy-lift businesses.
In 2025, cargo volumes across several industrial categories also increased. Machinery shipments rose 76% year on year, wind energy equipment volumes increased 55%, engineering equipment shipments rose 73%, and port machinery volumes increased 150%.
The semi-submersible division reported an 8.30-percentage-point improvement in gross margin in 2025, while the conventional heavy-lift division recorded a 4.51-percentage-point decline. These figures illustrate differences in segment performance during 2025 and should not be treated as 2026 third-quarter results.
The company has also outlined a further 14-vessel multipurpose heavy-lift fleet expansion involving eight newbuildings and six long-term bareboat charters, each covering vessels of approximately 60,000 dwt.
The proposed additions form part of its fleet development plans and should not be assumed to have been included in the 206 vessels reported at the end of September.
At the consolidated level, profitability improved during the first nine months of 2026.
The company’s reported revenue of RMB22.635 billion and cost of sales of approximately RMB16.800 billion imply gross profit of about RMB5.835 billion, compared with approximately RMB3.570 billion in the corresponding period of 2025.
The resulting nine-month gross margin was approximately 25.78%, compared with 21.49% a year earlier.
Using the difference between the nine-month and first-half consolidated financial statements, standalone third-quarter gross profit was approximately RMB2.489 billion, representing a gross margin of about 30.39%.
Both margin figures are calculated from reported consolidated financial data. They do not represent separately disclosed margins for heavy-lift ships, multipurpose vessels, semi-submersible vessels or car carriers.
The company’s weighted average return on equity reached 14.85% during the first nine months, an increase of 6.14 percentage points year on year.
Profit excluding non-recurring items accounted for approximately 98% of attributable net profit over the same period.
The third-quarter results demonstrate higher revenue and consolidated profitability alongside the expansion of the company’s operating fleet. However, the quarterly report does not disclose sufficient vessel-segment information to determine the individual contributions of heavy-lift, multipurpose, semi-submersible and car carrier operations to the latest profit increase.
The financial statements for the period ending 30 September 2026 were unaudited.