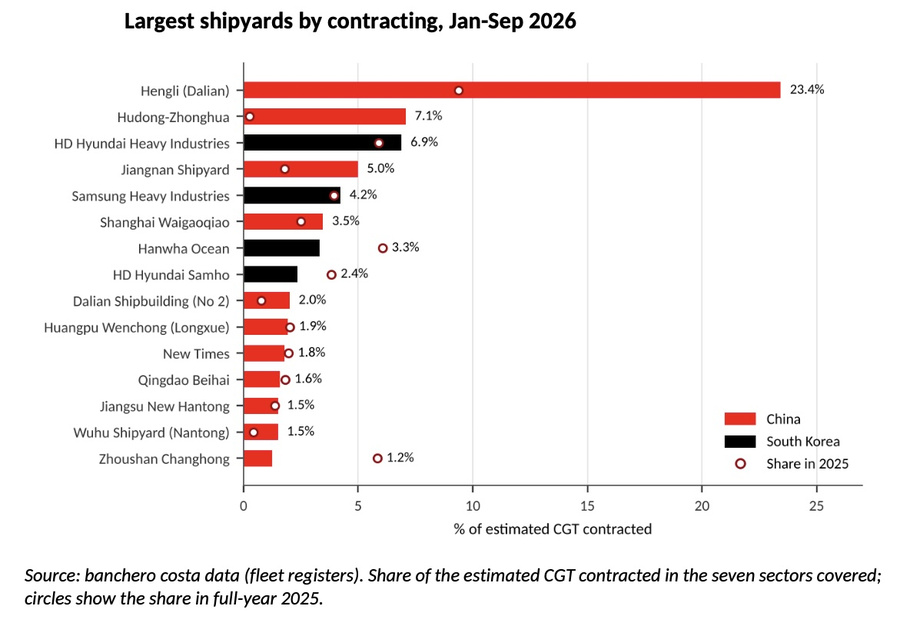
Hengli Heavy Industry secured contracts for 276 vessels during the first nine months of 2026, taking a 23.4% share of global newbuilding orders by compensated gross tonnage (CGT) across seven major merchant shipping sectors, according to figures from shipbroker Banchero Costa.
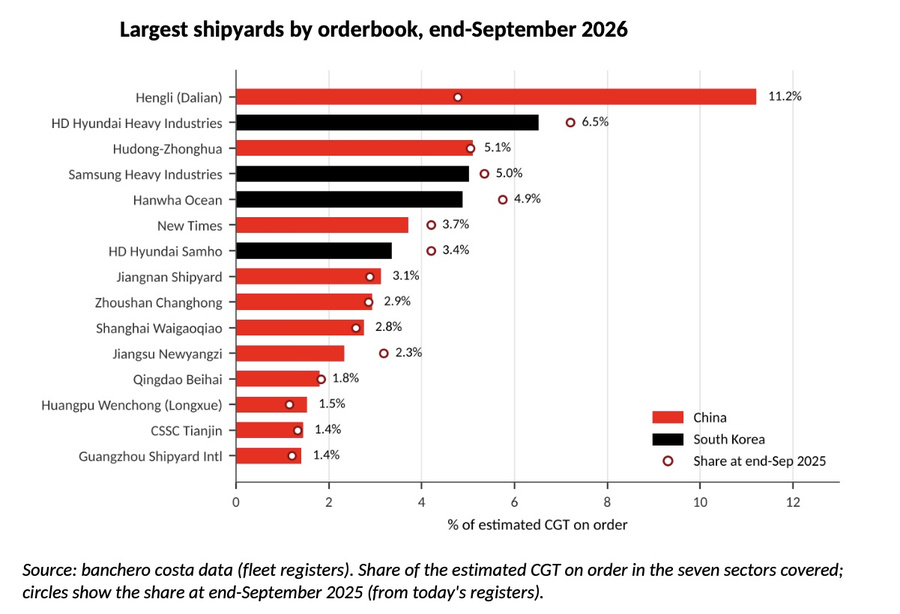
The Dalian-based shipbuilder has also accumulated an outstanding orderbook of 485 vessels, representing 11.2% of the global orderbook by CGT within the same seven sectors. Both figures place Hengli ahead of other individual shipyards covered by the broker’s analysis.
The volume of contracted vessels is accompanied by a substantial increase in scheduled deliveries. Banchero Costa’s figures show that Hengli is due to deliver 99 ships in 2027 and 199 in 2028, compared with 62 vessels completed during the first nine months of 2026.
Measured in CGT, its scheduled 2028 production is approximately 3.5 times the annualised output achieved during the first nine months of this year. The yard’s planned deliveries for 2028 would account for 12.6% of global deliveries across the seven merchant shipping sectors covered by the analysis.
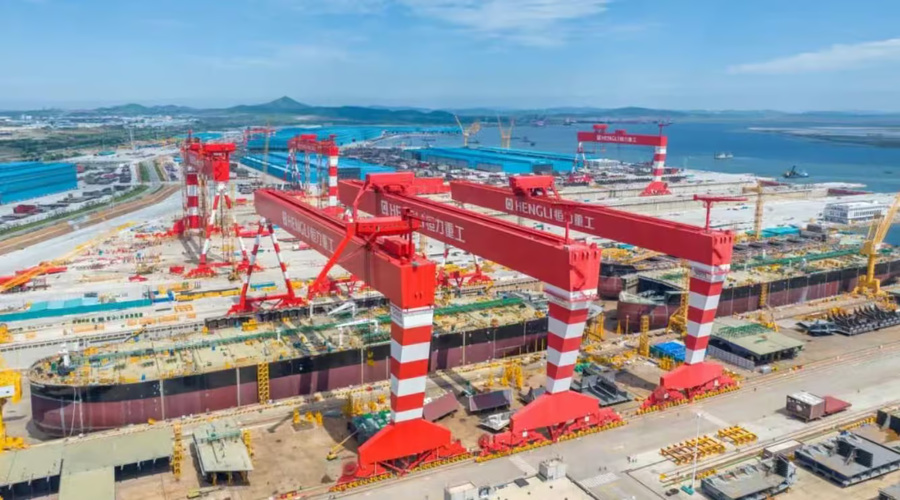
The expansion follows Hengli Group‘s acquisition of the former STX Dalian shipyard assets in 2022. Shipbuilding operations subsequently resumed, with the facility delivering four vessels in 2024 and 17 in 2025 before increasing deliveries to 62 during the January–September 2026 period.
To support its expanding production programme, Hengli has undertaken an RMB13.5 billion shipyard expansion project. The investment includes two 2,000-tonne gantry cranes, each spanning 256 metres, alongside additional manufacturing facilities for marine engines and other essential shipbuilding equipment.
The increase in activity has also been reflected in the financial results of Hengli’s Shanghai-listed parent, Guangdong Songfa Ceramics.
According to the company’s reported third-quarter financial results, revenue for the first nine months of 2026 reached RMB37.774 billion, an increase of 221.25% from the same period a year earlier. Net profit attributable to shareholders rose 424.87% to RMB6.673 billion.
Third-quarter attributable net profit alone reached RMB3.064 billion, up 390.87% year on year and exceeding the company’s net profit for the whole of 2025.
Hengli’s new contracts during the January–September period included 117 containerships, 100 crude oil tankers and 39 bulk carriers.
Its 23.4% share of newly contracted CGT compares with 9.4% for the full year of 2025. Among competing individual shipyards, Hudong-Zhonghua Shipbuilding accounted for 7.1% of newbuilding CGT contracted during the first nine months of 2026, followed by South Korea’s HD Hyundai Heavy Industries with 6.9%.
Hengli’s outstanding orderbook share, meanwhile, increased from 4.8% a year earlier to 11.2%, according to the figures reported by Banchero Costa.
The concentration of new contracts at recently established or restarted facilities extends beyond Hengli. The shipbroker estimates that such shipyards secured 32.8% of newbuilding contracts by CGT across the seven sectors in the first nine months of 2026, with the majority of this activity concentrated in China.
The resulting delivery schedules represent a significant increase in planned shipbuilding output. Across Chinese shipyards, bulk carrier and tanker deliveries scheduled for 2028 total 89.1 million deadweight tonnes (dwt). This compares with China’s previous annual record of 62.6 million dwt for the two vessel categories in 2011.
Banchero Costa expects some vessels currently scheduled for delivery in 2027 and 2028 to be completed in subsequent years as shipyards work through their contracted construction programmes.